tariffs

Department of Commerce Issues New Duty-Free Code for 232 Tariffs 

On April 27, 2026, the Department of Commerce published a Federal Register notice adding a new duty-free code in the Harmonized Tariff Schedule of the United States (HTSUS). The addition resolves a discrepancy for goods classified under HTSUS Chapters for steel, aluminum, and copper that were subject to 232 tariff classification even though they did not contain any of these elements. The provision, subheading 9903.82, applies retroactively to April 6, 2026. 

Recent 232 Developments 

This notice is the latest in a series of adjustments to 232 tariffs on steel, copper, iron, and aluminum.  

On April 2, 2026, the President issued a proclamation strengthening Section 232 actions to adjust imports of aluminum, steel, and copper, continuing to cite national security concerns and the need to reinforce domestic metals industries. Key elements of the proclamation include: a tiered tariff structure and some products exempt from Sec. 232 tariffs, and manufacturing drawback claims. Read more here. 

CBP has attempted to help importers navigate 232 tariffs. The agency recently published  FAQs and CSMS messages on steel and aluminum about how to calculate and report the value of the steel and aluminum content of steel and aluminum derivative articles.  

232 has been a hot topic at the Court of International Trade (CIT) as well. There is a current case challenging how CBP has been valuing and […]
By |2026-04-30T11:25:15-04:00April 30, 2026|Import, tariffs|0 Comments

CAPE Phase 1 is Here

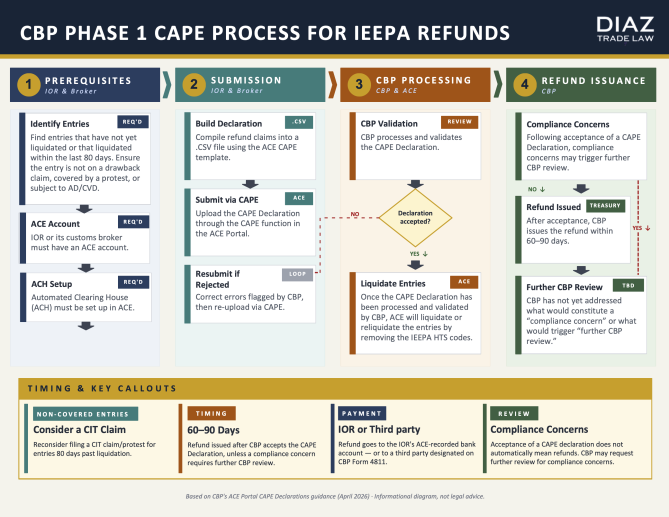
On April 20, 2026, CBP launched Phase 1 of the Consolidated Administration and Processing of Entries (CAPE). Importers of record (IORs) and licensed customs brokers may now file CAPE Declarations through ACE.

Tariff Refund Process

CBP has specified the actions required for requesting refunds:

  1. The Importer of Record (IOR) or its customs broker must have an ACE account.
  2. ACH must be set up in ACE (using a U.S. bank account).
  3. The IOR or its customs broker must submit the request for refund (CAPE Declaration) via CAPE in the ACE system.

The CAPE Declaration must be submitted as a .CSV file in ACE along with the following certification:

“I attest to the best of my knowledge and belief that: (1) the country of origin, entry type, Harmonized Tariff Schedule of the United States (HTSUS) classification(s), and valuation for each entry number is true and correct; and (2) the goods were not entered in violation of any applicable United States law, order, or rule. I understand that if I make or cause others to make material false statements or omissions to CBP, including in connection with a request for tariff reimbursement, I may be subject to criminal prosecution and civil liability, including but not limited to under 18 U.S.C. §§ 1001, 542, 545, 19 USC § 1592, and 31 U.S.C. § 3729(a).”

Once the CAPE Declaration has been processed and validated by CBP, ACE will liquidate or reliquidate the entries by removing the IEEPA HTS codes.  Refunds will be issued directly to the IOR’s bank account recorded in ACE or to a party the IOR has designated to receive refunds on its behalf via CBP Form 4811. Lastly, after the CAPE […]

By |2026-04-23T13:04:08-04:00April 23, 2026|tariffs|0 Comments

Tariff and Macroeconomic Risk Disclosures:

Lessons from Recent Shareholder Litigation Against Dow and Tronox

Authors:  

Jennifer Diaz, President, Diaz Trade Law
Amber Pirson, Attorney, Diaz Trade Law 

Recent securities class actions against Dow Inc. and Tronox Holdings plc underscore the growing litigation risk associated with tariff‑related and broader economic disclosures in periodic reports, earnings calls, and investor communications. These cases highlight how shareholder plaintiffs are scrutinizing statements that characterize tariffs and related headwinds as manageable, temporary, or hypothetical when subsequent developments suggest a more pronounced or foreseeable impact. 

As public companies continue to navigate volatile trade policy, supply chain disruption, and demand uncertainty, these lawsuits provide concrete guidance on how the SEC’s disclosure framework—particularly risk factors and Management’s Discussion and Analysis (MD&A) “known trends” disclosures—may be applied in hindsight by regulators and private litigants. 

Regulatory Framework: Risk Factors and Known Trends 

SEC rules make clear that companies must disclose certain risks to investors. For example, Item 105 of Regulation S‑K requires companies to disclose material risks that make an investment speculative or risky, while Item 303 requires MD&A discussion of known trends, events, or uncertainties reasonably likely to have a material impact on financial condition or operating results. In this context, tariffs – particularly where they affect costs, pricing, demand, or dividends – have increasingly been viewed as classic “known trends,” rather than contingent or […]

IEEPA Tariff Refund Updates

Recent developments surrounding tariffs imposed under the International Emergency Economic Powers Act (IEEPA) have created both opportunity and uncertainty for U.S. importers. With the U.S. Supreme Court ruling that IEEPA-based tariffs are unlawful, many companies understandably assume that refunds will follow automatically. In reality, that is far from guaranteed.  

For importers seeking to recover duties paid under these tariffs, a proactive legal and compliance strategy is essential.  

Recent Updates at the CIT 

On March 27, 2026, Judge Eaton issued an Order requiring CBP to liquidate or reliquidate all entries without the IEEPA duties. This Order applies to (1) unliquidated entries, (2) liquidated entries being protested, and (3) final liquidated entries. See CIT Order Dated March 27, 2026.

On March 31, 2026, CBP reported progress in creating the Consolidated Administration and Processing of Entries (CAPE), which will allow importers to submit refund requests.

On April 1, 2026, Judge Eaton ordered CBP to report on the progression of CAPE on April 14, 2026. In addition, in this Order, Judge Eaton encouraged importers to enroll in the ACH program because CBP will now only issue refunds electronically. Further, regarding liquidated entries, Judge Eaton stated that “importers should be aware of the option to file protests.   

On April 6, 2026, the plaintiff in the anchor case, Atmus Filtration, filed a Notice of Dismissal, thereby dropping from the case. However, the refund process […]

By |2026-04-15T02:41:27-04:00April 14, 2026|tariffs|0 Comments

New Executive Order Adjusting Imports of Aluminum, Steel, and Copper into the United States

Authors:

Jennifer Diaz, President, Diaz Trade Law
Amber Pirson, Attorney, Diaz Trade Law

On April 2, 2026, the President issued a proclamation strengthening Section 232 actions to adjust imports of aluminum, steel, and copper, continuing to cite national security concerns and the need to reinforce domestic metals industries. 

Key elements include: a tiered tariff structure and some products exempt from Sec. 232 tariffs, effective at 12:01 am on April 6, 2026; and manufacturing drawback claims.  

Generally, tariffs will be assessed to the full value of imported products, “regardless of their metal content,” with reduced rates for certain products from the United Kingdom (UK) and the same 200% ad valorem duty for subject metal articles from Russia. 

  • Aluminum and steel articles, most copper articles, and certain derivative articles of aluminum and steel…  
    • 50%, unless either the 25% or 10% rates listed below can apply. 
      • 25% for UK products, the aluminum content of which is composed entirely of aluminum that was smelted or most recently cast in the UK, or the steel content of which is composed entirely of steel that was melted and poured in the UK. 
      • 10% for derivative articles, steel or copper content, when the metal content was smelted and cast in the U.S. 
  • For certain copper and […]
Go to Top